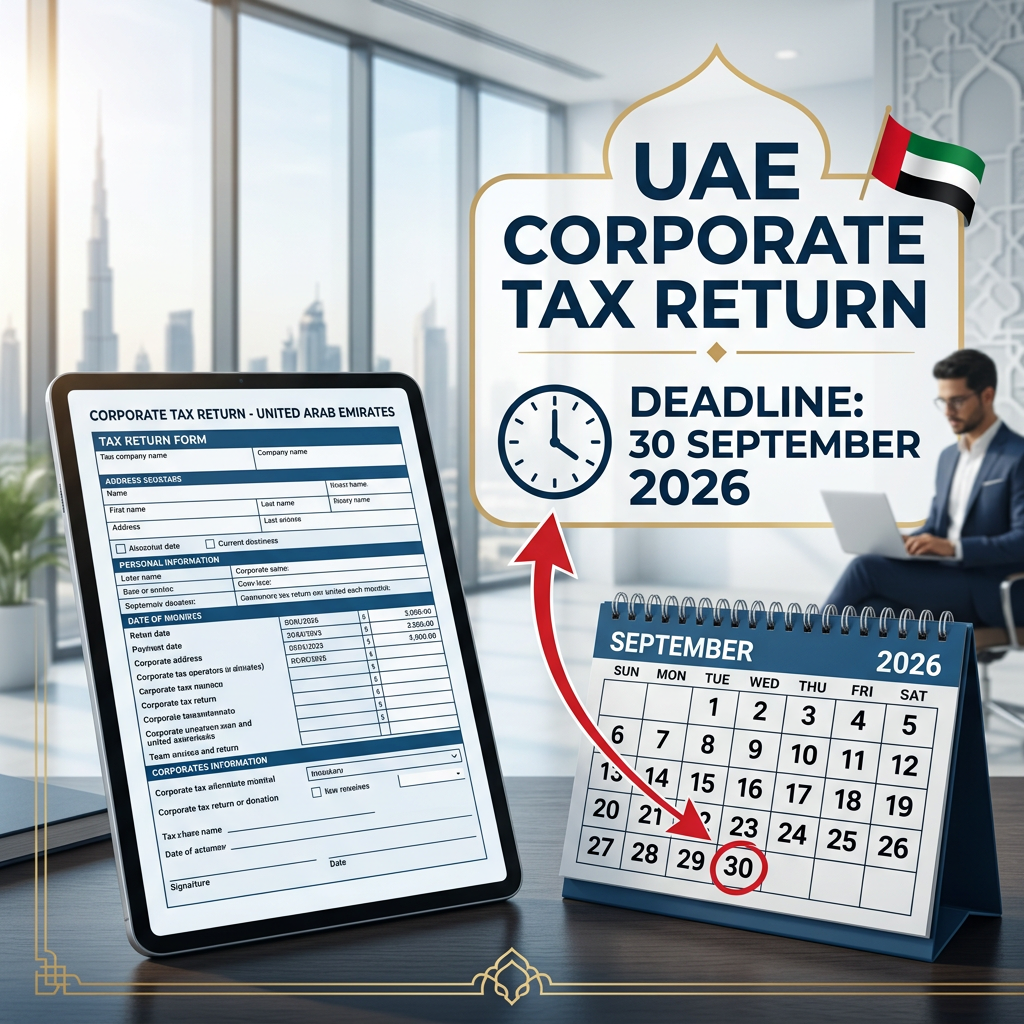
If your financial year ended on 31 December 2025, your first corporate tax return is due by 30 September 2026. That is a little over two weeks away.
We are writing this now because of a pattern in the questions reaching us: a lot of founders believe they are outside this. Some because they are in a free zone at 0 percent. Some because they elected Small Business Relief. Some because the company barely traded, or did not trade at all.
In almost every one of those cases, the filing obligation still applies. Here is who needs to act, what happens if you do not, and one piece of genuinely good news that has not travelled as widely as it should.
The Deadline, and Whether It Is Actually Yours
The corporate tax return and payment are due nine months after the end of your financial year.
For a calendar-year business — year end 31 December 2025 — that lands on 30 September 2026. This covers the majority of UAE companies, which is why that date is everywhere at the moment.
If your financial year ends on a different date, your deadline is different. A 31 March year end means 31 December. A 30 June year end means 31 March of the following year. Check your own year end rather than assuming the September date applies to you — and equally, do not relax because you have heard the deadline is in December for someone else.
Three Groups Who Think They Are Exempt, and Are Not
This is where most of the confusion sits, and all three of these come up weekly.
1. Free Zone Companies Paying 0 Percent
Qualifying for the 0 percent rate does not remove the filing obligation. Every free zone entity must register and file annually — including one expecting 0 percent on all of its income.
There is an additional reason to take this seriously. Filing on time is part of maintaining QFZP eligibility. Treating the return as optional because the tax is nil puts the very status that produces the nil result at risk.
2. Businesses That Elected Small Business Relief
Small Business Relief means you are treated as having no taxable income. It does not mean you have nothing to submit.
The relief is claimed through the return. No return, no election. Companies under AED 3 million in revenue that assumed the relief handled everything are the group we worry about most, because the assumption feels reasonable and is wrong.
3. Companies With No Revenue at All
Dormant companies, pre-revenue startups, entities set up and never traded — all file. Every taxable person files, including those owing zero.
A company that made no money and files nothing still accrues penalties. That is a painful way to discover the rule.
What Late Filing Costs
Late filing penalties run at AED 500 per month for the first twelve months, rising to AED 1,000 per month after that.
Late payment of tax owed is charged at 14 percent per annum on the unpaid balance, applied monthly until settled.
The structure matters more than the headline numbers. These accrue monthly and quietly. A dormant company that never filed is not sitting at a one-off fine — it is accumulating, and the total surfaces later, often at licence renewal or when someone finally engages an accountant.
Some Good News: ESR Is No Longer a Filing Obligation
This one deserves more attention than it has had.
Economic Substance Regulations notifications and reports were an annual burden for years. Cabinet Decision 98 of 2024 closed the ESR machinery, and ESR is no longer a 2026 filing obligation.
The substance concept did not disappear — it moved. For free zone entities it now lives inside corporate tax, through the QFZP regime’s adequate substance condition. So substance still matters, but as part of your tax position rather than as a separate annual filing.
If you have ESR notifications in your compliance calendar for this year, or a provider still quoting you for ESR filings, that is worth a conversation.
The Quiet One: UBO Filings
Ultimate beneficial owner obligations attract far less attention than corporate tax and carry fines that are, in places, considerably larger.
The UBO register must be filed within 60 days of incorporation. After that, any change to a beneficial owner’s details, any share transfer, or any shift in control must be reported to the registrar within 15 days.
That 15-day window is where companies slip. It is short, it is triggered by events people do not think of as filings, and nobody sends a reminder.
Penalties escalate steeply: second violations up to AED 50,000, third violations up to AED 100,000 plus possible licence suspension for up to twelve months.
If you have changed shareholders, adjusted shareholdings, or altered control arrangements in the past year and did not file within 15 days, that is worth checking now rather than at renewal.
VAT: The Penalty Regime Changed This Year
If you are VAT registered, note that the rules shifted under Cabinet Decision 129/2025.
Late filing starts at AED 1,000 for a first violation, rising to AED 2,000 for a repeat within 24 months. From 14 April 2026, late payment moved to a flat 14 percent per annum, calculated monthly on the unpaid balance.
Separately, failing to register within 30 days of crossing the mandatory threshold carries an AED 10,000 penalty. Businesses growing quickly cross the AED 375,000 threshold sooner than they expect — this is worth tracking monthly rather than reviewing annually.
What to Do in the Next Two Weeks
Confirm your financial year end. Everything follows from this. Check the licence and your incorporation documents rather than going from memory.
Confirm you are registered for corporate tax. Registration and filing are separate steps. If registration was never completed, that is the first problem to solve, and it is more urgent than the return itself.
Get your financial statements in order. If you are claiming QFZP status, remember that audited financial statements are required regardless of revenue. If you have not started that process, an honest conversation with an accountant this week is better than a scramble on the 29th.
Decide your relief position deliberately. Small Business Relief and QFZP status are mutually exclusive and both are claimed through the return. This is a decision, not a default.
If you are going to be late, file anyway. Penalties accrue monthly. Filing late is meaningfully better than not filing, and the gap widens every month.
Four Misconceptions Worth Clearing Up
“My accountant handles it.” Possibly — but confirm they are actually engaged for the corporate tax return, not just bookkeeping or VAT. These are frequently separate engagements, and the assumption that one covers the other is a common and expensive gap.
“I registered, so I am compliant.” Registration and filing are different obligations. A registered company that does not file accrues penalties exactly as an unregistered one would.
“I will deal with it at licence renewal.” Tax filings and licence renewal run on separate tracks, but they meet eventually — unresolved obligations can complicate your standing when renewal comes around. The order that works is tax first.
“The company is closing anyway.” Liquidation does not erase outstanding filings. In practice, unfiled returns make a clean closure harder and slower, and the obligations follow the company until they are settled.
If You Have Done Nothing So Far
It is worth saying plainly: this is recoverable.
Late registration, a missed return, unfiled UBO changes — these are common, they are fixable, and the sums involved are manageable when addressed now. What turns them expensive is time. Penalties compound monthly, and problems tend to surface at licence renewal, when they block the renewal itself.
Two weeks is enough to register, prepare a straightforward return, and file. It is not enough to complete a first statutory audit comfortably, so if that applies to you, prioritise accordingly and get advice on sequencing.
A Necessary Note
This is general information rather than tax advice, and the rules here have changed repeatedly — Cabinet Decision 98 of 2024 on ESR, Cabinet Decision 129/2025 on VAT penalties, Ministerial Decisions through 2025 on free zone activities and audits.
Deadlines depend on your specific financial year end and your registration status. Confirm your own position with the FTA portal or a qualified tax adviser rather than relying on any general article, this one included.
Over to You
A genuine question for anyone further along than we have assumed here: for those who have already filed a UAE corporate tax return, how did it go? Was the FTA portal straightforward, and did your accountant’s estimate match the eventual cost?
And for anyone who has not started — what is the actual blocker? In our experience it is usually bookkeeping that was never set up properly rather than the return itself, but we would like to know if that matches your situation.
Leave a comment. If there is a specific scenario worth covering properly — dormant companies, mid-year incorporations, businesses with a non-calendar year end — say so and we will write it up.
And if you are reading this close to the deadline and unsure where you stand, get in touch. Our consultations are free, and at this point in the month a fifteen-minute conversation about whether you need to file is worth having.